GOOGL / G17 / 2026-10-12
Google G17:独立PE的6M与12M触达校准Google G17: independent P/E calibrated for 6M and 12M touchGoogle G17:獨立PE的6M與12M觸達校準
当前G17试验计算值,未采用Current G17 trial values, not adopted當前G17試驗計算值,未採用
研究日期2026-10-12;财务、利率与价格评价截止仍冻结于2026-10-06,最新财务期2026Q2。以下不是10月12日新行情或新财报后的重算。Research date: October 12, 2026. Financial inputs, rates and price evaluation remain frozen at October 6, 2026, with latest financial period 2026Q2. These are not refreshed October 12 quotes or a post-earnings revaluation.研究日期2026-10-12;財務、利率與價格評價截止仍凍結於2026-10-06,最新財務期2026Q2。以下不是10月12日新行情或新財報後的重算。
| 期限与用途Horizon and role期限與用途 | 经营EPS代理Operating-EPS proxy經營EPS代理 | 独立PE / 目标PEIndependent / target P/E獨立PE / 目標PE | G17计算值G17 calculated valueG17計算值 | 参考日期 / 截止日Snapshot / deadline參考日期 / 截止日 |
|---|---|---|---|---|
| 0M · G16条件公平估计,沿用G16 conditional estimate, unchangedG16條件公平估計,沿用 | 12.9502 | 24.5946× | $318.51 | 2026-10-06 |
| 6M · G17期间触达候选,未采用G17 attainable candidate, not adoptedG17期間觸達候選,未採用 | 13.7238 | 21.3879× | $293.52 | 2027-04-06 |
| 12M · G17期间触达候选,未采用G17 attainable candidate, not adoptedG17期間觸達候選,未採用 | 15.2232 | 21.8197× | $332.16 | 2027-10-06 |
0M精确保留G16条件公平估计;6M、12M学习的是期间可能触达的市场目标,而非期限结束那天的公平价值。PE完全不从当天股价倒算;历史市场校准也不等于已完成现金流、普通股资本桥和资本成本核对的DCF内在价值。0M preserves G16’s conditional estimate exactly. 6M and 12M learn market targets that may be reached within the window, rather than fair values on the deadline itself. No multiple is solved backward from today’s stock price. Historical-market calibration is not a DCF intrinsic valuation with completed cash-flow, common-equity and cost-of-capital reconciliation.0M精確保留G16條件公平估計;6M、12M學習的是期間可能觸達的市場目標,而非期限結束那天的公平價值。PE完全不從當天股價倒算;歷史市場校準也不等於已完成現金流、普通股資本橋和資本成本核對的DCF內在價值。
G17未通过替换门槛:13项失败、5项通过。个股页继续单列G16的0M条件公平估计$318.51,以及G05保留的6M $368.45、12M $464.42。不同版本分别标示用途,不构成一套混合新模型。G17 failed replacement: thirteen gates fail and five pass. The equity page continues to show G16’s separate conditional 0M estimate of $318.51 and G05’s retained 6M / 12M forecasts of $368.45 / $464.42. Versions retain separate purposes; they do not constitute one combined model.G17未通過替換門檻:13項失敗、5項通過。個股頁繼續單列G16的0M條件公平估計$318.51,以及G05保留的6M $368.45、12M $464.42。不同版本分別標示用途,不構成一套混合新模型。
怎样优化6M与12M的独立PEHow independent 6M and 12M target P/E is calibrated怎樣優化6M與12M的獨立PE
三期EPS完全沿用原G05口径:0M/6M增长半衰期HL4、12M HL8,按日计算目标日起NTM窗口。Core EPS=经营利润×0.85÷起点稀释股数,是经营盈利代理,并非GAAP净EPS或分析师共识。0M倍数和价格精确保留G16;仅新加两个期限各自的标量校准。All EPS paths preserve the original G05 basis: growth half-life HL4 at 0M/6M, HL8 at 12M, and day-weighted target-date NTM windows. Core EPS = operating income × 0.85 / origin diluted shares, an operating-earnings proxy rather than GAAP net EPS or analyst consensus. 0M multiple and price preserve G16 exactly; the only new parameters are scalar corrections for the two future horizons.三期EPS完全沿用原G05口徑:0M/6M增長半衰期HL4、12M HL8,按日計算目標日起NTM窗口。Core EPS=經營利潤×0.85÷起點稀釋股數,是經營盈利代理,並非GAAP淨EPS或分析師共識。0M倍數和價格精確保留G16;僅新加兩個期限各自的標量校準。
每个历史月点的标签是其后完整6M或12M常规时段最高价÷当时同口径EPS_h。只有期限已严格结束于本次预测起点之前的标签才能训练;未到期即使已经触达也不用。分别取最近60个合法成熟月,按两年半衰期降权,并在同一已知财务季度内平衡权重。Each historical month is labeled with its complete next-6M or next-12M regular-session peak / its own then-known same-basis EPS_h. Training requires the deadline to have ended strictly before the new forecast origin; pending labels are excluded even if a touch has been observed. Select the latest sixty legal mature months per horizon, apply a two-year weight half-life and balance within each known financial vintage.每個歷史月點的標籤是其後完整6M或12M常規時段最高價÷當時同口徑EPS_h。只有期限已嚴格結束於本次預測起點之前的標籤才能訓練;未到期即使已經觸達也不用。分別取最近60個合法成熟月,按兩年半衰期降權,並在同一已知財務季度內平衡權重。
历史标签去趋势时用本次预测起点已经合法估计的G16成长与利率斜率,而非历史标签当时的拟合系数。训练来源及两个期限不同,因此6M与12M可以形成不同目标PE;PE调低来自这层历史目标校准,不能直接解释为成长走弱、加息或利率的因果惩罚。Historical labels are detrended with G16 growth and rate slopes legally estimated at the new prediction origin, not with coefficients originally fitted at each historical label date. Training pools differ by horizon, so 6M and 12M may have different target P/E. A lower target multiple comes from this historical target-calibration layer and cannot be interpreted directly as weaker growth, tightening or a causal interest-rate penalty.歷史標籤去趨勢時用本次預測起點已經合法估計的G16成長與利率斜率,而非歷史標籤當時的擬合係數。訓練來源及兩個期限不同,因此6M與12M可以形成不同目標PE;PE調低來自這層歷史目標校準,不能直接解釋為成長走弱、加息或利率的因果懲罰。
| 当前期限拟合Current horizon fit當前期限擬合 | 6M | 12M |
|---|---|---|
| 合法成熟月数 / 财务季度Eligible mature months / financial vintages合法成熟月數 / 財務季度 | 60 / 20 | 56 / 19 |
| logPE修正 dLog-P/E correction dlogPE修正 d | -0.13970237 | -0.11971345 |
| PE乘数 exp(d)P/E factor exp(d)PE乘數 exp(d) | 0.86961702 | 0.88717462 |
| 目标PETarget P/E目標PE | 21.387863× | 21.819685× |
| 最后合法标签截止日Latest eligible label deadline最後合法標籤截止日 | 2026-09-30 | 2026-09-30 |
展开冻结公式与损失含义Show the frozen equation and loss interpretation展開凍結公式與損失含義
y_i,h = log(complete_peak_i,h / own_origin_CoreEPS_i,h)
a_i,h,t = y_i,h − bg_G16(t) × (g_i − g_t) − br_G16(t) × (r_i − r_t) − logPE_G16(t)
d_h = argmin_d { sum[w_i × rho_0.10(a_i,h,t − d)] + 0.5 × d² }
PE_h = exp(logPE_G16(t) + d_h); Target_h = CoreEPS_h × PE_h
rho_tau(u) = tau × u for u >= 0; (tau − 1) × u for u < 0
w_i = 2^(−age_days / 730.5) / eligible_count_same_financial_vintage量化水平固定0.10、先验惩罚固定1;权重不归一化。正二次项令一维目标有唯一解,求解断点或子梯度不是多个可择优模型。0.10损失优先惩罚未触达方向的过高预测;它不保证未来90%触达,也不直接等同于平均相对峰值差的最小化。没有参数网格、分析师拟合或看到评分后的额外折扣。The quantile is fixed at 0.10 and prior penalty at one; weights are not normalized. The positive quadratic term gives the one-dimensional objective a unique solution. Numerical breakpoints or subgradients are not alternative selectable models. The 0.10 loss penalizes excessive targets more heavily; it does not guarantee a 90% future hit probability or directly minimize mean relative peak gap. There is no parameter grid, analyst fitting or extra haircut chosen after inspecting scores.量化水平固定0.10、先驗懲罰固定1;權重不歸一化。正二次項令一維目標有唯一解,求解斷點或子梯度不是多個可擇優模型。0.10損失優先懲罰未觸達方向的過高預測;它不保證未來90%觸達,也不直接等同於平均相對峯值差的最小化。沒有參數網格、分析師擬合或看到評分後的額外折扣。
早期12M只保留先验,不能写成已训练目标Early 12M uses only the prior, not a trained horizon target早期12M只保留先驗,不能寫成已訓練目標
2021-10-27及2022-02-02两个12M起点没有已成熟期限标签。冻结模型规定空校准损失只剩d²/2,其唯一解d=0,目标PE精确等于G16先验;必须标记PRIOR_ONLY。20个季度全部保留,不能把这两行删掉再宣称五年全样本改进。At the 12M origins of October 27, 2021 and February 2, 2022, no matured horizon labels exist. The frozen hierarchy leaves only d²/2 when its optional calibration pool is empty, whose unique solution is d=0 and whose target P/E exactly equals the G16 prior. These rows are labeled PRIOR_ONLY. All twenty quarters remain; deleting these rows would not demonstrate a full five-year improvement.2021-10-27及2022-02-02兩個12M起點沒有已成熟期限標籤。凍結模型規定空校準損失只剩d²/2,其唯一解d=0,目標PE精確等於G16先驗;必須標記PRIOR_ONLY。20個季度全部保留,不能把這兩行刪掉再宣稱五年全樣本改進。
必要财务、股数、EPS或G16基础估计缺失,仍判不可估,不用空标签规则补猜。训练月数多于独立财报数,窗口重叠;即使有标签,也不能视为同样数量的独立样本。Missing required financial inputs, shares, EPS or G16 base estimates still means not estimable; the empty-label rule cannot fabricate them. Training month counts exceed distinct financial vintages and their windows overlap. Having labels does not create that many independent samples.必要財務、股數、EPS或G16基礎估計缺失,仍判不可估,不用空標籤規則補猜。訓練月數多於獨立財報數,窗口重疊;即使有標籤,也不能視為同樣數量的獨立樣本。
仅校准已启动的共同样本诊断Diagnostic on the common calibration-active sample only僅校準已啓動的共同樣本診斷
| 版本Model版本 | 期限Horizon期限 | 成熟触达Mature hits成熟觸達 | 触达率Hit rate觸達率 | 平均绝对峰值差Mean absolute peak gap平均絕對峯值差 | 平均最高价/目标Mean peak/target平均最高價/目標 | 目标低于起点价Targets below origin price目標低於起點價 | 待到期Pending待到期 |
|---|---|---|---|---|---|---|---|
| G05 | 6M | 16/18 | 88.89% | 15.80% | 119.64% | 0 | 2 |
| G16 | 6M | 14/18 | 77.78% | 24.29% | 123.73% | 9 | 2 |
| G17 | 6M | 16/18 | 88.89% | 30.86% | 141.23% | 15 | 2 |
| G05 | 12M | 13/14 | 92.86% | 27.37% | 139.66% | 3 | 4 |
| G16 | 12M | 13/14 | 92.86% | 32.36% | 143.62% | 4 | 4 |
| G17 | 12M | 12/14 | 85.71% | 48.22% | 185.42% | 11 | 4 |
6M无先验独占行;12M成熟样本由16行减至14行。三模型按相同剩余起点比较,仅作诊断,不参与采用;正式评分保留全部原起点。6M has no prior-only rows. Removing the two prior-only 12M rows reduces its mature diagnostic sample from sixteen to fourteen. All three models use the identical remaining origins. This is diagnostic only, not adoption evidence; the formal score retains every original origin.6M無先驗獨佔行;12M成熟樣本由16行減至14行。三模型按相同剩餘起點比較,僅作診斷,不參與採用;正式評分保留全部原起點。
过去五年:先触达,再比较最高价差Five years: touch first, then proximity to the window high過去五年:先觸達,再比較最高價差
使用2021Q3至2026Q2的20个财报后起点;6M成熟18/待2,12M成熟16/待4。同一批起点同时计算G05、G16和G17,不改成月末预测或删去不利季度。Use twenty post-earnings origins from 2021Q3 through 2026Q2: eighteen mature / two pending at 6M, sixteen mature / four pending at 12M. G05, G16 and G17 share the identical origins; no month-end evaluation or removal of adverse quarters is substituted.使用2021Q3至2026Q2的20個財報後起點;6M成熟18/待2,12M成熟16/待4。同一批起點同時計算G05、G16和G17,不改成月末預測或刪去不利季度。
预测点为每季度财报发布后的首个完整常规交易日收盘。从下一交易日至日历期限截止日(含),任何一天常规时段日内最高价严格高于未四舍五入目标,就算触达;截止日后行情不借用。先看成熟触达率,再看平均|目标÷完整期间最高价−1|。平均最高价/目标只是描述,不能按越高越好选模。Each quarterly forecast is formed at the first complete regular-session close after earnings. From the next session through the calendar deadline inclusive, any regular-session daily high strictly above the unrounded target counts as a hit; prices after the deadline are not borrowed. Evaluate mature hit rate first, then mean |target / complete-window maximum high − 1|. Mean peak/target is descriptive and is not maximized for selection.預測點為每季度財報發佈後的首個完整常規交易日收盤。從下一交易日至日曆期限截止日(含),任何一天常規時段日內最高價嚴格高於未四捨五入目標,就算觸達;截止日後行情不借用。先看成熟觸達率,再看平均|目標÷完整期間最高價−1|。平均最高價/目標只是描述,不能按越高越好選模。
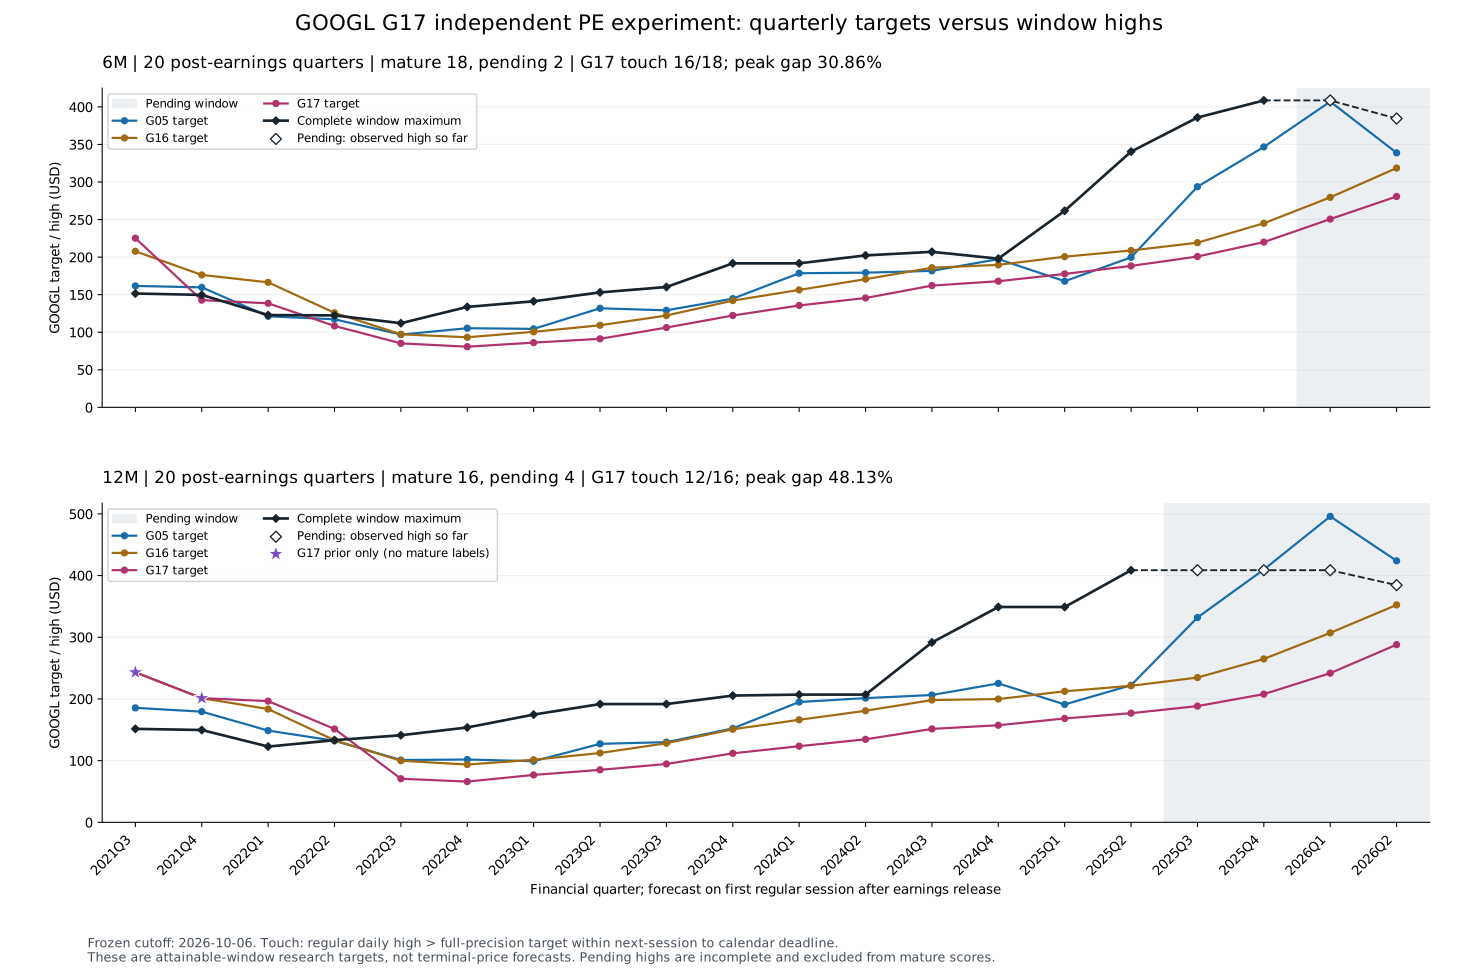
| 版本Model版本 | 期限Horizon期限 | 成熟触达Mature hits成熟觸達 | 触达率Hit rate觸達率 | 平均绝对峰值差Mean absolute peak gap平均絕對峯值差 | 平均最高价/目标Mean peak/target平均最高價/目標 | 目标低于起点价Targets below origin price目標低於起點價 | 待到期Pending待到期 |
|---|---|---|---|---|---|---|---|
| G05 | 6M | 16/18 | 88.89% | 15.80% | 119.64% | 0 | 2 |
| G05 | 12M | 13/16 | 81.25% | 26.59% | 132.52% | 3 | 4 |
| G16 | 6M | 14/18 | 77.78% | 24.29% | 123.73% | 9 | 2 |
| G16 | 12M | 13/16 | 81.25% | 34.25% | 134.21% | 4 | 4 |
| G17 | 6M | 16/18 | 88.89% | 30.86% | 141.23% | 15 | 2 |
| G17 | 12M | 12/16 | 75.00% | 48.13% | 170.78% | 11 | 4 |
6M触达率由G16的77.78%提升至88.89%,只追平G05;峰值差扩大至30.86%,差于G05的15.80%和G16的24.29%。12M触达率降至75.00%,低于两基准的81.25%;峰值差扩大至48.13%。当前目标变低并没有同时改善触达与最高价接近程度。6M hit rate rises from G16’s 77.78% to 88.89%, only matching G05. Peak gap widens to 30.86%, worse than G05’s 15.80% and G16’s 24.29%. 12M hits fall to 75.00%, below both references at 81.25%, while peak gap widens to 48.13%. Lower current targets did not jointly improve touch and proximity to the window high.6M觸達率由G16的77.78%提升至88.89%,只追平G05;峯值差擴大至30.86%,差於G05的15.80%和G16的24.29%。12M觸達率降至75.00%,低於兩基準的81.25%;峯值差擴大至48.13%。當前目標變低並沒有同時改善觸達與最高價接近程度。
待到期窗口只公布截至冻结日已观察的最高价与触达状态,不视作完整期间最高价;不进入成熟触达率、平均触达比例或完整峰值差。低于起点价格的目标须单列,避免保守低目标制造高准确率印象。Pending windows show only the peak and touch observed through the frozen cutoff. That peak is not a complete-window maximum, and pending rows stay outside mature hit rates, mean attainment ratios and complete peak gaps. Below-origin targets are reported separately so conservative low targets do not create a false impression of accuracy.待到期窗口只公佈截至凍結日已觀察的最高價與觸達狀態,不視作完整期間最高價;不進入成熟觸達率、平均觸達比例或完整峯值差。低於起點價格的目標須單列,避免保守低目標製造高準確率印象。
固定G05上涨目标共同样本Fixed common G05 upside-target cohort固定G05上漲目標共同樣本
| 版本Model版本 | 期限Horizon期限 | 成熟触达Mature hits成熟觸達 | 触达率Hit rate觸達率 | 平均绝对峰值差Mean absolute peak gap平均絕對峯值差 | 平均最高价/目标Mean peak/target平均最高價/目標 | 目标低于起点价Targets below origin price目標低於起點價 | 待到期Pending待到期 |
|---|---|---|---|---|---|---|---|
| G05 | 6M | 16/18 | 88.89% | 15.80% | 119.64% | 0 | 0 |
| G16 | 6M | 14/18 | 77.78% | 24.29% | 123.73% | 9 | 0 |
| G17 | 6M | 16/18 | 88.89% | 30.86% | 141.23% | 15 | 0 |
| G05 | 12M | 10/13 | 76.92% | 24.21% | 126.34% | 0 | 0 |
| G16 | 12M | 10/13 | 76.92% | 32.74% | 126.19% | 1 | 0 |
| G17 | 12M | 9/13 | 69.23% | 46.26% | 157.47% | 8 | 0 |
该共同样本预先由G05目标不低于起点价格定义;三模型共用分母。G17自己的低目标不能改变样本资格。共同样本仍未通过替换门槛。This cohort is fixed beforehand by G05 targets at least as high as the origin price. All three models use the same denominator. G17’s lower targets cannot redefine eligibility. The common cohort also fails replacement.該共同樣本預先由G05目標不低於起點價格定義;三模型共用分母。G17自己的低目標不能改變樣本資格。共同樣本仍未通過替換門檻。
20个财报后季度:目标与期间最高价逐次记录All twenty post-earnings quarters: targets and window highs20個財報後季度:目標與期間最高價逐次記錄
两表保留同一20个起点,分别列6M及12M。目标都是起点一次形成的冻结预测;最高价是该次目标的观察窗口聚合,不是在最高价出现时重算模型。期末未成熟的行只显示已观察最高,峰值差留空。Both tables preserve the same twenty origins, separately for 6M and 12M. Targets are frozen forecasts made once at each origin; highs aggregate that target’s observation window and do not involve refitting at the peak date. Pending rows show only the observed high, with complete peak gap left blank.兩表保留同一20個起點,分別列6M及12M。目標都是起點一次形成的凍結預測;最高價是該次目標的觀察窗口聚合,不是在最高價出現時重算模型。期末未成熟的行只顯示已觀察最高,峯值差留空。
6M
| 财务季度Financial quarter財務季度 | 财报后预测点Post-earnings origin財報後預測點 | G05 6M | G16 6M | G17 6M | 完整最高 / 待期已观察最高Complete high / pending observed high完整最高 / 待期已觀察最高 | 状态与G17触达Status and G17 touch狀態與G17觸達 | G17绝对峰值差G17 absolute peak gapG17絕對峯值差 | 训练月 / 财务季Training months / vintages訓練月 / 財務季 | 校准模式Calibration mode校準模式 |
|---|---|---|---|---|---|---|---|---|---|
| 2021Q3 | 2021-10-27 | $161.63 | $207.78 | $225.23 | $151.55 2022-02-02 | 成熟 · 未触达Mature · miss成熟 · 未觸達 | 48.62% | 2 / 1 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2021Q4 | 2022-02-02 | $159.76 | $176.29 | $142.70 | $149.68 2022-02-03 | 成熟 · 触达Mature · hit成熟 · 觸達 | 4.66% | 6 / 3 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2022Q1 | 2022-04-27 | $121.24 | $166.44 | $138.52 | $122.85 2022-05-04 | 成熟 · 未触达Mature · miss成熟 · 未觸達 | 12.75% | 8 / 3 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2022Q2 | 2022-07-27 | $117.23 | $125.86 | $108.36 | $122.43 2022-08-16 | 成熟 · 触达Mature · hit成熟 · 觸達 | 11.50% | 11 / 4 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2022Q3 | 2022-10-26 | $96.90 | $97.26 | $85.21 | $112.02 2023-03-29 | 成熟 · 触达Mature · hit成熟 · 觸達 | 23.93% | 14 / 5 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2022Q4 | 2023-02-03 | $105.35 | $93.29 | $80.74 | $133.74 2023-07-28 | 成熟 · 触达Mature · hit成熟 · 觸達 | 39.63% | 18 / 7 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q1 | 2023-04-26 | $104.47 | $100.53 | $86.18 | $141.22 2023-10-12 | 成熟 · 触达Mature · hit成熟 · 觸達 | 38.97% | 20 / 7 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q2 | 2023-07-26 | $131.89 | $109.29 | $91.26 | $153.05 2024-01-25 | 成熟 · 触达Mature · hit成熟 · 觸達 | 40.37% | 23 / 8 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q3 | 2023-10-25 | $129.15 | $122.24 | $106.21 | $160.22 2024-04-12 | 成熟 · 触达Mature · hit成熟 · 觸達 | 33.71% | 26 / 9 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q4 | 2024-01-31 | $144.73 | $142.16 | $122.30 | $191.75 2024-07-10 | 成熟 · 触达Mature · hit成熟 · 觸達 | 36.22% | 29 / 10 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q1 | 2024-04-26 | $178.57 | $156.35 | $135.66 | $191.75 2024-07-10 | 成熟 · 触达Mature · hit成熟 · 觸達 | 29.25% | 32 / 11 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q2 | 2024-07-24 | $179.29 | $170.70 | $145.57 | $202.29 2025-01-21 | 成熟 · 触达Mature · hit成熟 · 觸達 | 28.04% | 35 / 12 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q3 | 2024-10-30 | $181.71 | $185.86 | $162.09 | $207.05 2025-02-04 | 成熟 · 触达Mature · hit成熟 · 觸達 | 21.71% | 38 / 13 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q4 | 2025-02-05 | $197.33 | $189.69 | $167.93 | $197.95 2025-07-24 | 成熟 · 触达Mature · hit成熟 · 觸達 | 15.17% | 42 / 15 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q1 | 2025-04-25 | $167.92 | $200.58 | $177.65 | $261.68 2025-10-24 | 成熟 · 触达Mature · hit成熟 · 觸達 | 32.11% | 44 / 15 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q2 | 2025-07-24 | $199.71 | $208.82 | $188.31 | $340.49 2026-01-13 | 成熟 · 触达Mature · hit成熟 · 觸達 | 44.70% | 47 / 16 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q3 | 2025-10-30 | $293.73 | $219.22 | $200.80 | $385.84 2026-04-30 | 成熟 · 触达Mature · hit成熟 · 觸達 | 47.96% | 50 / 17 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q4 | 2026-02-05 | $346.71 | $245.07 | $220.01 | $408.61 2026-05-18 | 成熟 · 触达Mature · hit成熟 · 觸達 | 46.16% | 54 / 19 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2026Q1 | 2026-04-30 | $407.08 | $279.57 | $250.62 | $408.61 · 仅观察observed only僅觀察 2026-05-18 | 待到期 · 已观察触达Pending · touch observed待到期 · 已觀察觸達 | — | 56 / 19 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2026Q2 | 2026-07-23 | $338.82 | $318.60 | $280.72 | $384.48 · 仅观察observed only僅觀察 2026-08-05 | 待到期 · 已观察触达Pending · touch observed待到期 · 已觀察觸達 | — | 59 / 20 | 成熟标签校准Mature-label calibration成熟標籤校準 |
12M
| 财务季度Financial quarter財務季度 | 财报后预测点Post-earnings origin財報後預測點 | G05 12M | G16 12M | G17 12M | 完整最高 / 待期已观察最高Complete high / pending observed high完整最高 / 待期已觀察最高 | 状态与G17触达Status and G17 touch狀態與G17觸達 | G17绝对峰值差G17 absolute peak gapG17絕對峯值差 | 训练月 / 财务季Training months / vintages訓練月 / 財務季 | 校准模式Calibration mode校準模式 |
|---|---|---|---|---|---|---|---|---|---|
| 2021Q3 | 2021-10-27 | $185.53 | $243.12 | $243.12 | $151.55 2022-02-02 | 成熟 · 未触达Mature · miss成熟 · 未觸達 | 60.43% | 0 / 0 | 仅G16先验G16 prior only僅G16先驗 |
| 2021Q4 | 2022-02-02 | $179.41 | $201.30 | $201.30 | $149.68 2022-02-03 | 成熟 · 未触达Mature · miss成熟 · 未觸達 | 34.49% | 0 / 0 | 仅G16先验G16 prior only僅G16先驗 |
| 2022Q1 | 2022-04-27 | $148.73 | $183.62 | $196.52 | $122.85 2022-05-04 | 成熟 · 未触达Mature · miss成熟 · 未觸達 | 59.96% | 2 / 1 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2022Q2 | 2022-07-27 | $132.20 | $133.04 | $151.39 | $133.24 2023-07-27 | 成熟 · 未触达Mature · miss成熟 · 未觸達 | 13.62% | 5 / 2 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2022Q3 | 2022-10-26 | $101.04 | $99.88 | $70.71 | $141.22 2023-10-12 | 成熟 · 触达Mature · hit成熟 · 觸達 | 49.93% | 8 / 3 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2022Q4 | 2023-02-03 | $101.85 | $93.71 | $66.06 | $153.78 2024-01-29 | 成熟 · 触达Mature · hit成熟 · 觸達 | 57.04% | 12 / 4 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q1 | 2023-04-26 | $99.11 | $101.47 | $76.88 | $174.71 2024-04-26 | 成熟 · 触达Mature · hit成熟 · 觸達 | 56.00% | 14 / 5 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q2 | 2023-07-26 | $127.24 | $112.43 | $85.09 | $191.75 2024-07-10 | 成熟 · 触达Mature · hit成熟 · 觸達 | 55.63% | 17 / 6 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q3 | 2023-10-25 | $130.01 | $128.23 | $94.63 | $191.75 2024-07-10 | 成熟 · 触达Mature · hit成熟 · 觸達 | 50.65% | 20 / 7 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2023Q4 | 2024-01-31 | $152.24 | $150.87 | $111.87 | $205.48 2025-01-31 | 成熟 · 触达Mature · hit成熟 · 觸達 | 45.56% | 23 / 8 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q1 | 2024-04-26 | $195.11 | $166.23 | $123.51 | $207.05 2025-02-04 | 成熟 · 触达Mature · hit成熟 · 觸達 | 40.35% | 26 / 9 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q2 | 2024-07-24 | $201.36 | $180.83 | $134.60 | $207.05 2025-02-04 | 成熟 · 触达Mature · hit成熟 · 觸達 | 34.99% | 29 / 10 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q3 | 2024-10-30 | $206.40 | $198.26 | $151.45 | $291.59 2025-10-30 | 成熟 · 触达Mature · hit成熟 · 觸達 | 48.06% | 32 / 11 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2024Q4 | 2025-02-05 | $225.16 | $199.83 | $157.38 | $349.00 2026-02-03 | 成熟 · 触达Mature · hit成熟 · 觸達 | 54.91% | 36 / 13 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q1 | 2025-04-25 | $191.12 | $212.41 | $168.41 | $349.00 2026-02-03 | 成熟 · 触达Mature · hit成熟 · 觸達 | 51.75% | 38 / 13 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q2 | 2025-07-24 | $222.23 | $221.37 | $176.97 | $408.61 2026-05-18 | 成熟 · 触达Mature · hit成熟 · 觸達 | 56.69% | 41 / 14 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q3 | 2025-10-30 | $331.96 | $234.67 | $188.42 | $408.61 · 仅观察observed only僅觀察 2026-05-18 | 待到期 · 已观察触达Pending · touch observed待到期 · 已觀察觸達 | — | 44 / 15 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2025Q4 | 2026-02-05 | $409.73 | $264.89 | $207.82 | $408.61 · 仅观察observed only僅觀察 2026-05-18 | 待到期 · 已观察触达Pending · touch observed待到期 · 已觀察觸達 | — | 48 / 16 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2026Q1 | 2026-04-30 | $495.88 | $307.07 | $241.82 | $408.61 · 仅观察observed only僅觀察 2026-05-18 | 待到期 · 已观察触达Pending · touch observed待到期 · 已觀察觸達 | — | 50 / 17 | 成熟标签校准Mature-label calibration成熟標籤校準 |
| 2026Q2 | 2026-07-23 | $423.88 | $352.44 | $288.01 | $384.48 · 仅观察observed only僅觀察 2026-08-05 | 待到期 · 已观察触达Pending · touch observed待到期 · 已觀察觸達 | — | 53 / 18 | 成熟标签校准Mature-label calibration成熟標籤校準 |
待到期窗口只公布截至冻结日已观察的最高价与触达状态,不视作完整期间最高价;不进入成熟触达率、平均触达比例或完整峰值差。低于起点价格的目标须单列,避免保守低目标制造高准确率印象。Pending windows show only the peak and touch observed through the frozen cutoff. That peak is not a complete-window maximum, and pending rows stay outside mature hit rates, mean attainment ratios and complete peak gaps. Below-origin targets are reported separately so conservative low targets do not create a false impression of accuracy.待到期窗口只公佈截至凍結日已觀察的最高價與觸達狀態,不視作完整期間最高價;不進入成熟觸達率、平均觸達比例或完整峯值差。低於起點價格的目標須單列,避免保守低目標製造高準確率印象。
近三年诊断:全触达仍不代表贴近最高价Three-year diagnostic: all hits still do not imply close peak estimates近三年診斷:全觸達仍不代表貼近最高價
近三年12个季度起点中,6M成熟10、12M成熟8。三模型都触达全部成熟目标,G17峰值差仍扩大至33.50%和47.87%。100%历史触达不能写成100%未来概率。The last three years contain twelve quarterly origins, with ten mature 6M and eight mature 12M windows. All three models hit every mature target, yet G17 peak gaps widen to 33.50% and 47.87%. A 100% historical hit rate is not a 100% future probability.近三年12個季度起點中,6M成熟10、12M成熟8。三模型都觸達全部成熟目標,G17峯值差仍擴大至33.50%和47.87%。100%歷史觸達不能寫成100%未來概率。
| 版本Model版本 | 期限Horizon期限 | 成熟触达Mature hits成熟觸達 | 触达率Hit rate觸達率 | 平均绝对峰值差Mean absolute peak gap平均絕對峯值差 | 平均最高价/目标Mean peak/target平均最高價/目標 | 目标低于起点价Targets below origin price目標低於起點價 | 待到期Pending待到期 |
|---|---|---|---|---|---|---|---|
| G05 | 6M | 10/10 | 100.00% | 19.09% | 126.66% | 0 | 2 |
| G05 | 12M | 8/8 | 100.00% | 27.77% | 144.27% | 0 | 4 |
| G16 | 6M | 10/10 | 100.00% | 24.33% | 135.91% | 6 | 2 |
| G16 | 12M | 8/8 | 100.00% | 31.47% | 149.42% | 1 | 4 |
| G17 | 6M | 10/10 | 100.00% | 33.50% | 153.96% | 9 | 2 |
| G17 | 12M | 8/8 | 100.00% | 47.87% | 195.02% | 7 | 4 |
分析师比较只有2/12精确同日记录Analyst comparison has only two of twelve exact same-day records分析師比較只有2/12精確同日記錄
三年12个季度只有2个保存的精确同日StockAnalysis平均12M目标,10个缺失。三模型使用同两条记录;不取较早、未来邻近或月末目标,不插值。以下是共识目标距离诊断,不是实际价格误差,也不能声称完成三年季度分析师验证。Only two of twelve three-year quarterly origins have saved exact same-day StockAnalysis mean 12M targets; ten are missing. All three models use the identical two records, without earlier, future-nearest, month-end or interpolated substitutes. The following measures disagreement with consensus, not realized-price error or a complete three-year quarterly analyst validation.三年12個季度只有2個保存的精確同日StockAnalysis平均12M目標,10個缺失。三模型使用同兩條記錄;不取較早、未來鄰近或月末目標,不插值。以下是共識目標距離診斷,不是實際價格誤差,也不能聲稱完成三年季度分析師驗證。
| 诊断 / 覆盖Diagnostic / coverage診斷 / 覆蓋 | G05 | G16 | G17 |
|---|---|---|---|
| 精确同日记录 / 应有季度Exact same-day records / required quarters精確同日記錄 / 應有季度 | 2 / 12 | 2 / 12 | 2 / 12 |
| 仅两条记录的平均绝对目标差Mean absolute target gap on only two records僅兩條記錄的平均絕對目標差 | 3.40% | 5.78% | 29.06% |
分析师目标不进入模型拟合与采用。商业原始逐日记录保留内部;公开页面只显示覆盖及聚合比较。Analyst targets do not enter fitting or adoption. Commercial raw daily records remain internal; this page publishes only coverage and aggregate comparison.分析師目標不進入模型擬合與採用。商業原始逐日記錄保留內部;公開頁面只顯示覆蓋及聚合比較。
采用判断:保留G16的0M与G05未来预测Decision: retain G16 at 0M and G05 future forecasts採用判斷:保留G16的0M與G05未來預測
G17未通过替换门槛:13项失败、5项通过。个股页继续单列G16的0M条件公平估计$318.51,以及G05保留的6M $368.45、12M $464.42。不同版本分别标示用途,不构成一套混合新模型。G17 failed replacement: thirteen gates fail and five pass. The equity page continues to show G16’s separate conditional 0M estimate of $318.51 and G05’s retained 6M / 12M forecasts of $368.45 / $464.42. Versions retain separate purposes; they do not constitute one combined model.G17未通過替換門檻:13項失敗、5項通過。個股頁繼續單列G16的0M條件公平估計$318.51,以及G05保留的6M $368.45、12M $464.42。不同版本分別標示用途,不構成一套混合新模型。
独立工程核验通过;未来目标的替换门槛仍失败Independent engineering checks passed; future-target replacement still failed獨立工程核驗通過;未來目標的替換門檻仍失敗
冻结18项条件要求两个期限全样本和共同G05上涨目标样本的触达率、峰值差均不劣于G05与G16,并分别至少有一项全样本严格改善。13项失败,因此工程核验即使通过,也不能自动采用G17。Eighteen frozen conditions require nonworse touch and peak gap versus both G05 and G16, at both horizons on the full panel and fixed common G05 upside-target cohort, plus at least one strict full-panel improvement against each reference. Thirteen fail. Engineering audit passage therefore cannot automatically adopt G17.凍結18項條件要求兩個期限全樣本和共同G05上漲目標樣本的觸達率、峯值差均不劣於G05與G16,並分別至少有一項全樣本嚴格改善。13項失敗,因此工程核驗即使通過,也不能自動採用G17。
展开18项冻结门槛Show all eighteen frozen gates展開18項凍結門檻
| 条件Condition條件 | 结果Result結果 |
|---|---|
| 6M 全样本:触达率不劣于G056M full panel: hit rate nonworse than G056M 全樣本:觸達率不劣於G05 | 通过Pass通過 |
| 6M 全样本:峰值差不劣于G056M full panel: peak gap nonworse than G056M 全樣本:峯值差不劣於G05 | 失败Fail失敗 |
| 6M 固定G05上涨目标共同样本:触达率不劣于G056M fixed common G05 upside cohort: hit rate nonworse than G056M 固定G05上漲目標共同樣本:觸達率不劣於G05 | 通过Pass通過 |
| 6M 固定G05上涨目标共同样本:峰值差不劣于G056M fixed common G05 upside cohort: peak gap nonworse than G056M 固定G05上漲目標共同樣本:峯值差不劣於G05 | 失败Fail失敗 |
| 12M 全样本:触达率不劣于G0512M full panel: hit rate nonworse than G0512M 全樣本:觸達率不劣於G05 | 失败Fail失敗 |
| 12M 全样本:峰值差不劣于G0512M full panel: peak gap nonworse than G0512M 全樣本:峯值差不劣於G05 | 失败Fail失敗 |
| 12M 固定G05上涨目标共同样本:触达率不劣于G0512M fixed common G05 upside cohort: hit rate nonworse than G0512M 固定G05上漲目標共同樣本:觸達率不劣於G05 | 失败Fail失敗 |
| 12M 固定G05上涨目标共同样本:峰值差不劣于G0512M fixed common G05 upside cohort: peak gap nonworse than G0512M 固定G05上漲目標共同樣本:峯值差不劣於G05 | 失败Fail失敗 |
| 6M 全样本:触达率不劣于G166M full panel: hit rate nonworse than G166M 全樣本:觸達率不劣於G16 | 通过Pass通過 |
| 6M 全样本:峰值差不劣于G166M full panel: peak gap nonworse than G166M 全樣本:峯值差不劣於G16 | 失败Fail失敗 |
| 6M 固定G05上涨目标共同样本:触达率不劣于G166M fixed common G05 upside cohort: hit rate nonworse than G166M 固定G05上漲目標共同樣本:觸達率不劣於G16 | 通过Pass通過 |
| 6M 固定G05上涨目标共同样本:峰值差不劣于G166M fixed common G05 upside cohort: peak gap nonworse than G166M 固定G05上漲目標共同樣本:峯值差不劣於G16 | 失败Fail失敗 |
| 12M 全样本:触达率不劣于G1612M full panel: hit rate nonworse than G1612M 全樣本:觸達率不劣於G16 | 失败Fail失敗 |
| 12M 全样本:峰值差不劣于G1612M full panel: peak gap nonworse than G1612M 全樣本:峯值差不劣於G16 | 失败Fail失敗 |
| 12M 固定G05上涨目标共同样本:触达率不劣于G1612M fixed common G05 upside cohort: hit rate nonworse than G1612M 固定G05上漲目標共同樣本:觸達率不劣於G16 | 失败Fail失敗 |
| 12M 固定G05上涨目标共同样本:峰值差不劣于G1612M fixed common G05 upside cohort: peak gap nonworse than G1612M 固定G05上漲目標共同樣本:峯值差不劣於G16 | 失败Fail失敗 |
| 相对G05至少一项全样本严格改善At least one strict full-panel improvement versus G05相對G05至少一項全樣本嚴格改善 | 失败Fail失敗 |
| 相对G16至少一项全样本严格改善At least one strict full-panel improvement versus G16相對G16至少一項全樣本嚴格改善 | 通过Pass通過 |
估值边界与下一步问题Valuation limits and the next research question估值邊界與下一步問題
0M精确保留G16条件公平估计;6M、12M学习的是期间可能触达的市场目标,而非期限结束那天的公平价值。PE完全不从当天股价倒算;历史市场校准也不等于已完成现金流、普通股资本桥和资本成本核对的DCF内在价值。0M preserves G16’s conditional estimate exactly. 6M and 12M learn market targets that may be reached within the window, rather than fair values on the deadline itself. No multiple is solved backward from today’s stock price. Historical-market calibration is not a DCF intrinsic valuation with completed cash-flow, common-equity and cost-of-capital reconciliation.0M精確保留G16條件公平估計;6M、12M學習的是期間可能觸達的市場目標,而非期限結束那天的公平價值。PE完全不從當天股價倒算;歷史市場校準也不等於已完成現金流、普通股資本橋和資本成本核對的DCF內在價值。
本轮显示,把期限最高价低分位学习叠加到独立PE上,容易出现过于保守的低目标:6M成熟18行有15行低于起点价格,12M成熟16行有11行。提高触达率必须同时约束最高价距离,不能用更低的目标作为成功定义。This trial shows that learning a low quantile of window peaks on top of independent P/E can produce overly conservative targets: fifteen of eighteen mature 6M targets and eleven of sixteen mature 12M targets lie below the origin price. Higher touch rates must be judged together with peak proximity; lower targets cannot define success by themselves.本輪顯示,把期限最高價低分位學習疊加到獨立PE上,容易出現過於保守的低目標:6M成熟18行有15行低於起點價格,12M成熟16行有11行。提高觸達率必須同時約束最高價距離,不能用更低的目標作為成功定義。
历史窗口重叠、过去多轮研究已查看同一时期,历史财务重建未认证为完整PIT快照,也未形成独立前瞻OOS。保留失败版本与预测;下一轮应先明确可容忍漏触达水平和低目标约束,再冻结新方案,不能看到本轮评分后修改G17。Windows overlap and the same period has been inspected across multiple generations. Historical financial reconstruction is not certified as a complete PIT archive, and there is no independent prospective OOS trial. Preserve the failed version and forecasts. A next candidate should first declare acceptable missed touches and limits on excessively low targets, then freeze a new protocol; G17 cannot be changed after inspecting its scores.歷史窗口重疊、過去多輪研究已查看同一時期,歷史財務重建未認證為完整PIT快照,也未形成獨立前瞻OOS。保留失敗版本與預測;下一輪應先明確可容忍漏觸達水平和低目標約束,再凍結新方案,不能看到本輪評分後修改G17。
Google完整版本与方法Complete Google versions and methodsGoogle完整版本與方法 · G16独立PE基础G16 independent P/E foundationG16獨立PE基礎 · 当前保留研究参考Current retained research references當前保留研究參考